For a few months now, I’ve felt that my eldest was ready to tackle the topic of investing in the stock market.
But hey, like any self-respecting teenager, she has her moments of “Yeah, well, what you’re saying is boring. What am I supposed to do with that info?!?”… alternating with moments of closeness and curiosity when she’s in the right frame of mind.
And one late afternoon in July (somewhere between six heatwaves…), I felt she was in the right frame of mind.
We were both in the living room, me reading a book, her on her smartphone, but in “I’m open to talking about life right now” mode haha. Mrs. MP was out with our other child. I told myself the opening was too good to pass up.
So I went for it:
How about we install your Interactive Brokers investing app [IBKR for short], the one where we put all your savings, so you can see how much you have and how it works?
Open-minded enough, she says yes, “if you want”. Because, you know, you shouldn’t show too much enthusiasm for an idea coming from your dad :D
Interactive Brokers GlobalTrader or IBKR Mobile?
Except I hadn’t prepared anything… So I’d forgotten which of the two apps I wanted her to install: Interactive Brokers GlobalTrader or IBKR Mobile?
I decided to keep it simple and go with “IBKR GlobalTrader”, which looks less complicated when you’re starting out.
If you want a comparison of the two apps, you can read my article here by the way (handy to have your own blog to find your own info haha): Interactive Brokers Switzerland: GlobalTrader or IBKR Mobile?

So we install IBKR GlobalTrader on her phone.
Then I share her login and password with her, and we land on the home screen.
The shock of the amount on her IBKR account (and the killer question)
Her first reaction was: “CHF 17'852.53!?! 🤯🤑”
She was shocked. Not frozen-shocked, more like impressed-shocked.
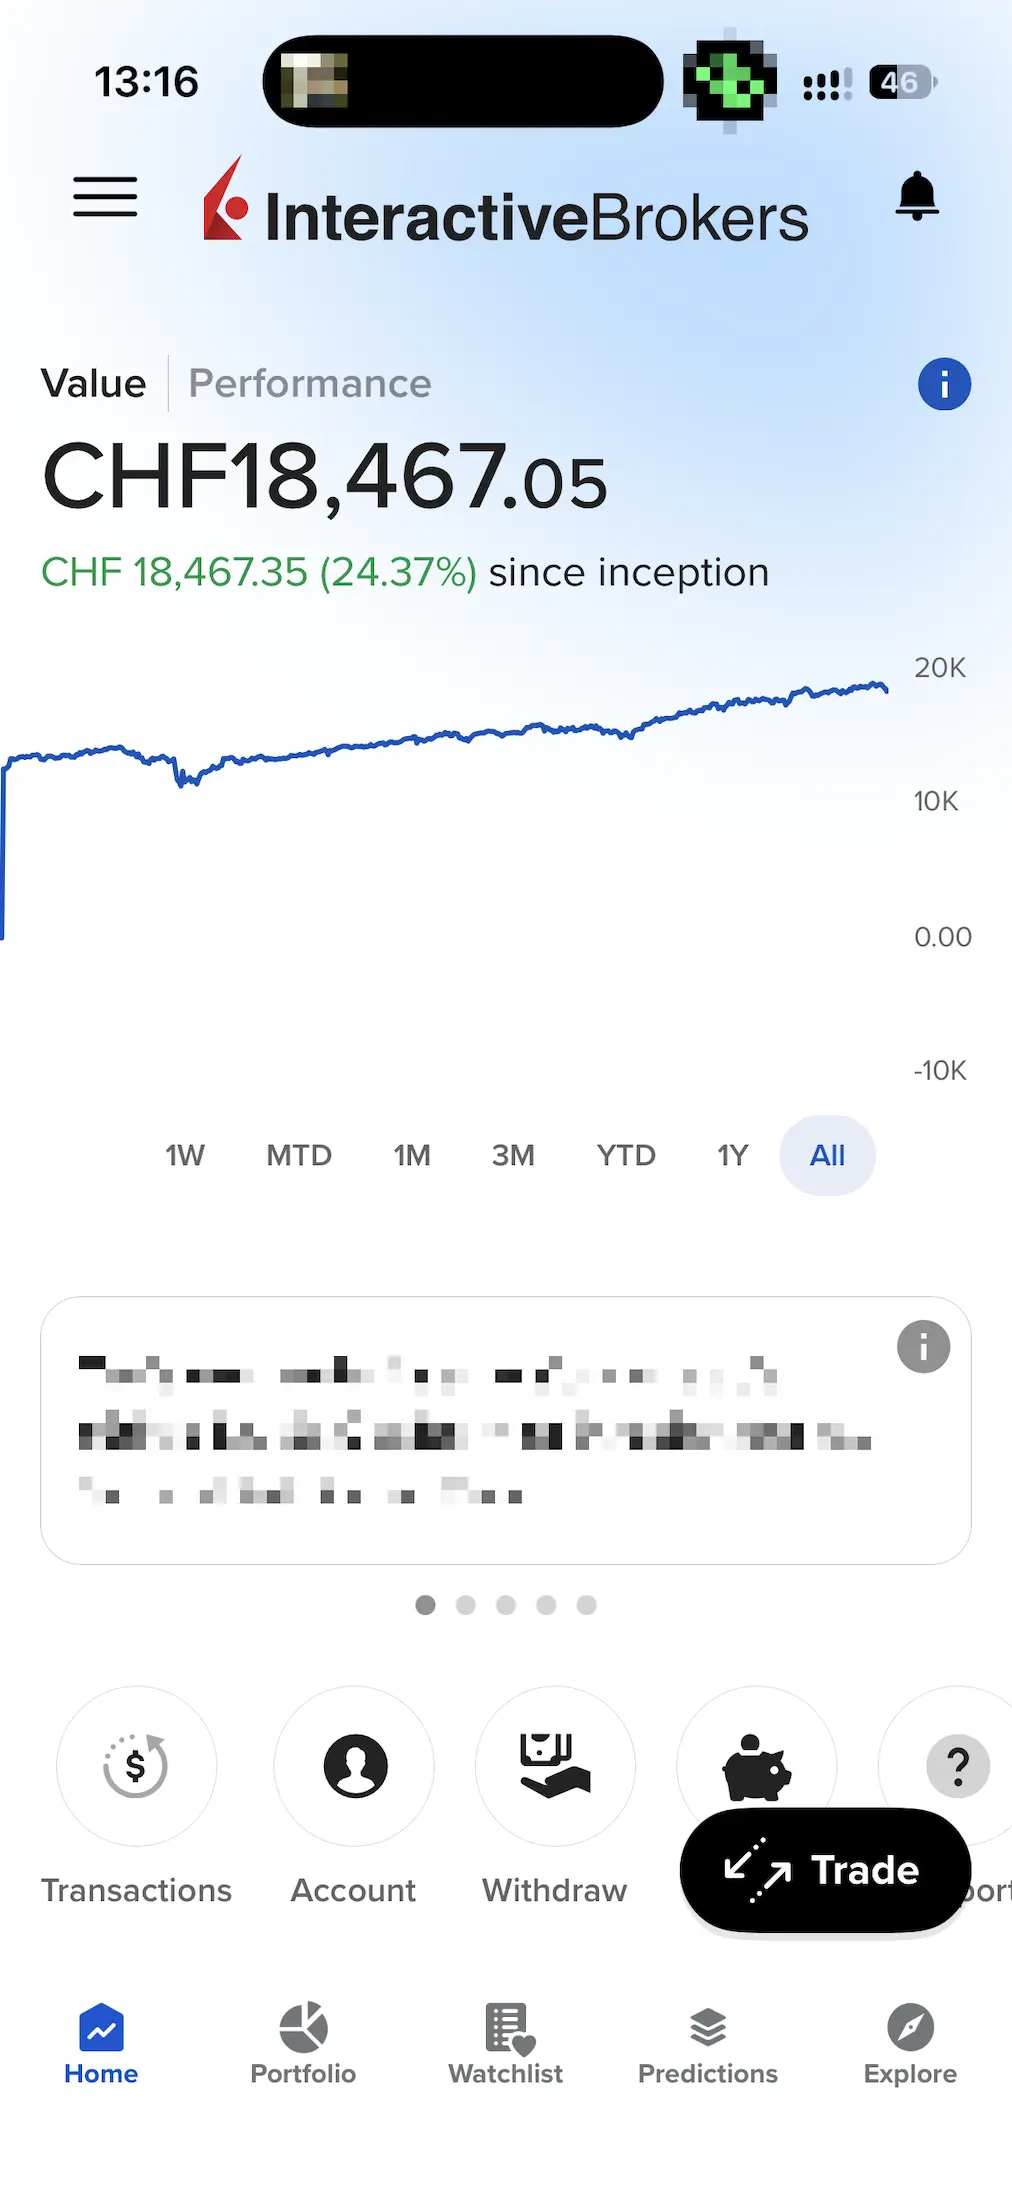
Her IBKR GlobalTrader home screen today, at CHF 18'467 versus CHF 17'852 that July evening. The money made babies in the meantime.
I admit that’s not nothing for a teenager. I would have loved my parents to set up the same thing for me and break that kind of news ;)
And then, the killer question:
So when can I use that?
“That” being the almost CHF 18k, haha.
I had already raised the topic with Mrs. MP, but we never really settled on a precise plan. So, like any self-respecting parent, you have to know how to improvise:
Well, listen, in principle, never.
Haha. No, but let’s say that around 25 or even 30, you’ll be allowed to dip into your dividends when you receive them.
BUT only for an important project, not for the latest iPhone.
The capital, on the other hand, the idea is that you never touch it, so you can see the effect of compound interest for yourself (you know, the thing that magically makes your money have babies).
Since she knows we have pretty clear rules about everything related to budget and money, she didn’t flinch.
A tad disappointed not to be able to blow it all in one day (no, I’m exaggerating, she didn’t even say that), but in the end, no big surprise.
I kept guiding her through the app to show her that we had started by putting CHF 50 into it every month since she was 2. And how she could see the dividends coming in every quarter (I explain that in How to check the profits you make on Interactive Brokers in 2026).
Then she followed up with three questions I wasn’t expecting…
Her 3 raw questions about IBKR, unfiltered
“If I sell, how much can I make?”
Her question was more about reassuring herself. Like, if she sold everything, how much would she get? (because, let’s be honest, it’s all pretty virtual).
Because yes, there’s the total value of the portfolio, and there’s also the capital gain.
So I explained that the total value figure of her portfolio was what she would get if she sold everything at once. Minus fees of a few cents or a few francs at most.
But I also explained that if the stock market crashed tomorrow and she sold that day, well, the amount would be lower. And likewise, if the market went up, she’d get more. Basically, it’s a snapshot at time T, and it’s different if you sell at time T+1.
And if she sold, it would take 1-2 seconds and bam, the corresponding cash would show up on the “USD” line of her portfolio.
Which brought us to the next question.
“Can I actually get that into my bank account?”
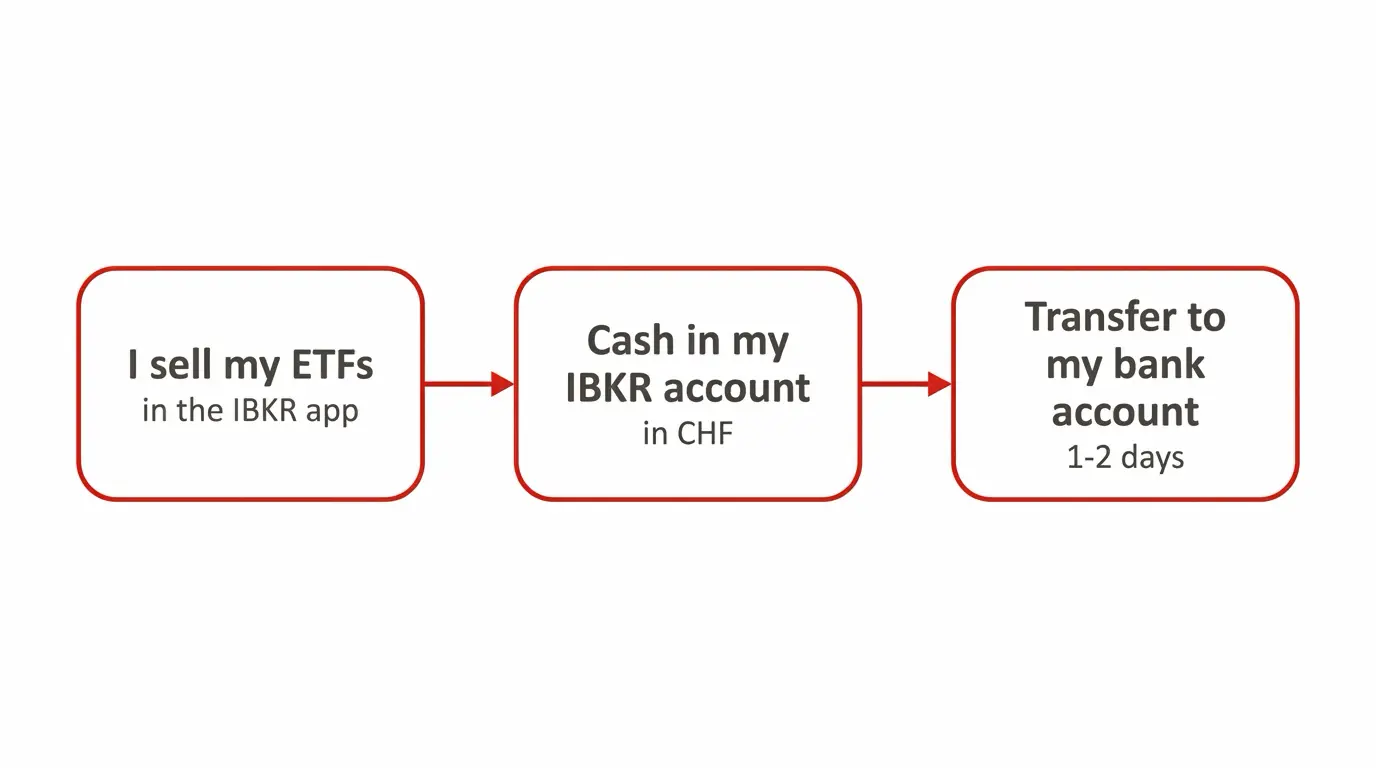
Because yes, selling your ETFs on IBKR is not the same as withdrawing money from your IBKR account.
And that’s a concept I explained to my teen in detail: your IBKR app is a real account, with a real account number, just like at the bank.
So if you want to get Swiss francs out of this account, well, just like with your regular bank account, you have to make a transfer from one account to another.
I was glad it clicked for her that yes, invested money is real. But no, it isn’t directly “liquid”, in the sense that you have to sell the ETFs before you can withdraw it.
And it was great to see her eyes sparkle with excitement at my conclusion: “So yes, to answer your original question: that amount, you can withdraw it to your own bank account (once you’ve sold your ETFs/stocks).”
And suddenly, I see her frown…
“But I only put CHF 12k into my IBKR account to begin with, right?”
Well, first, I clarified: “we” deposited CHF 12k into your account, my dear :D
Joking aside, I think that was the best question.
Or what a first encounter with compound interest looks like.
That’s when I answered with a huge smile:
Exactly. We put in ~CHF 12k, and today you have CHF 17'852.53. The difference is the magic of the stock market, with the value of companies growing while you sleep, and the magic of compound interest, where your money makes babies all by itself while you go about your business.
We had already touched on these topics when she talked about them in her economics class in secondary school. So she knew. But right there it suddenly became much (much!) more concrete, since it’s HER money :)
Side note: for those who pulled out their calculator to check whether CHF 50 per month matched the teen’s age, let me stop you, it doesn’t. And that’s normal, because the CHF 12k also includes several amounts received for her birthdays and other occasions from her grandparents.
An unforgettable last question.
But then came a moment when I was even prouder of her…
The moment I’m proudest of: locking the IBKR app
Several years ago, while we were talking about a private matter that had to stay within the family, I had explained the concept of confidentiality circles to our kids (what’s theirs alone [the smallest circle], what must stay within our immediate family, what can be discussed with the extended family, etc.).
So this time, to put Interactive Brokers in context, I explained to my eldest, before having her install the IBKR app, that for now she had to keep this information confidential, within the family.
Yes, you’ll tell me that for a blogger who promotes talking more about money, that’s rich, but I don’t want her to have problems with bullying or the like because she showed someone at school an amount in CHF. But I digress.
And so, as we were wrapping up the little introductory tour of Interactive Brokers, I reminded her: “Like with your e-banking app, these topics stay within the immediate family.”
And right then, without hesitation, I see her do something I knew about but had never applied myself: locking an app at launch.
So I ask her: “Wait, what are you doing?”
She retorts, in the most normal and obvious tone: “Well, since it’s the same as for my e-banking app, I’m turning on Face ID so nobody can open the app if I ever lend my phone to someone to watch a funny video or whatever.” (she has an iPhone)
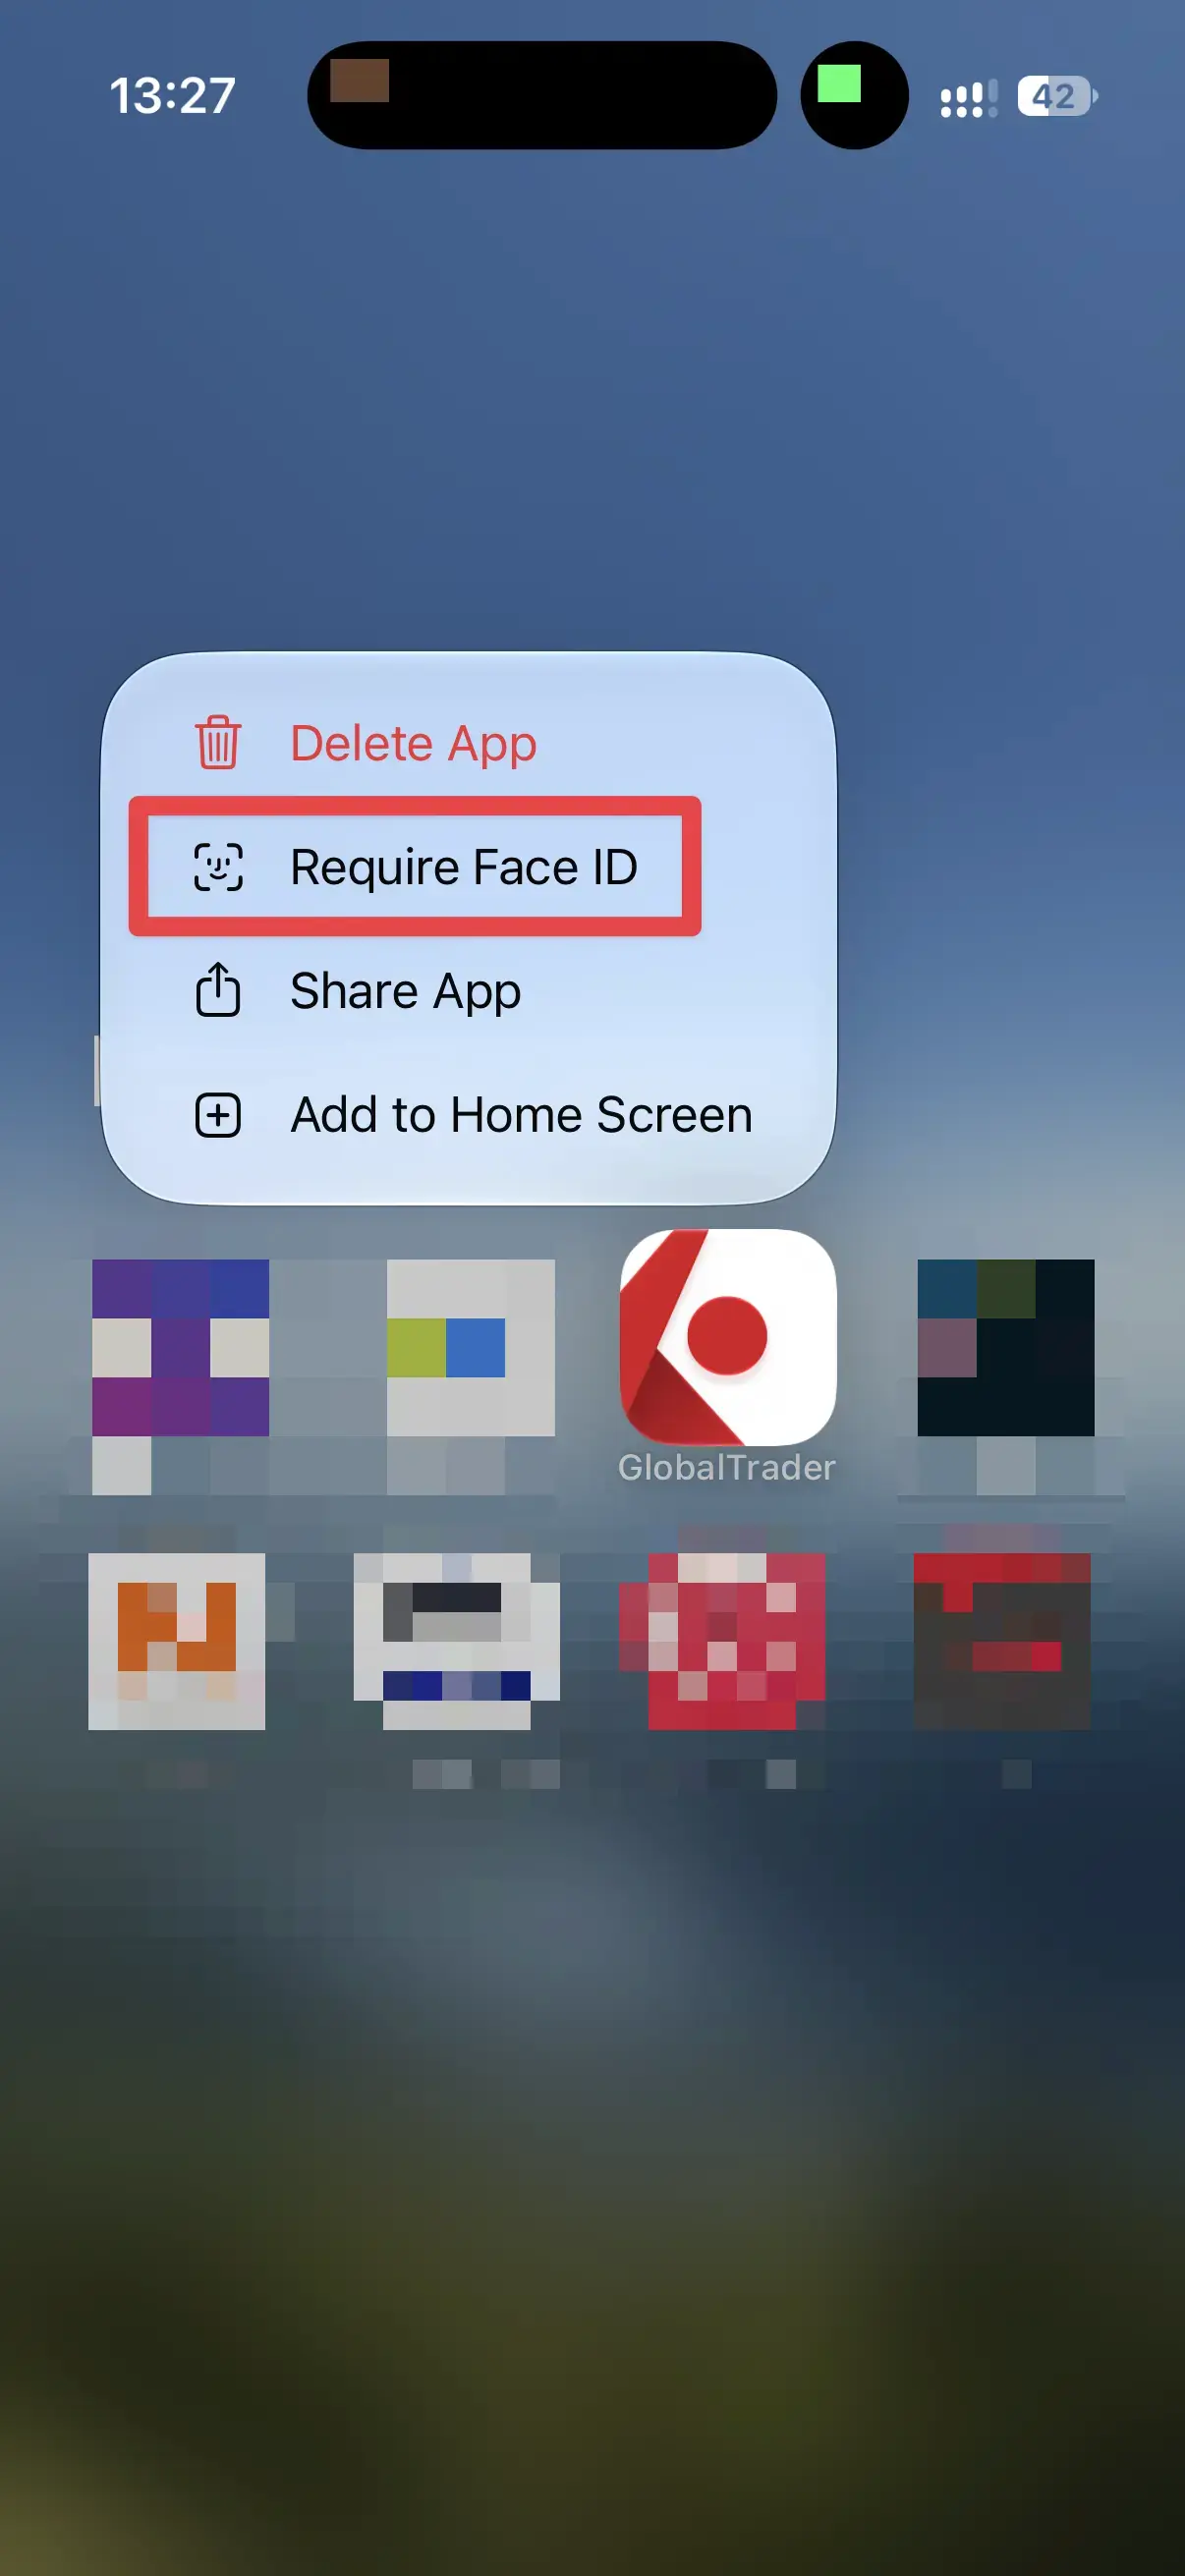
To lock the IBKR GlobalTrader app on iPhone, long-press the icon, then Require Face ID. The app won't open without your face anymore.
And it doesn’t end there.
I ask her how long ago she turned that on?!
She says: “Well, Dad, since I installed the e-banking app [several years ago] and you told me it was confidential”.
And adds: “Even my sibling has it on, you know. I showed them.”
I was stunned. With pride. Honestly, I think we didn’t get everything wrong on the parenting front. And that kind of moment, as parents, feels really good :D
Conclusion: introducing your child to the stock market through practice rather than theory
As in many areas of life, you can read as many books as you want, follow as many motivational Instagram accounts, or watch as many TikTok videos (🤮) admiring interior renovations, you’ll never learn as much as by doing.
I’ve made the same observation with their pocket money: their real questions came from managing their own money (including the famous “50% of everything you earn goes into savings” rule), not from listening to me. And a game of Ciao CASH triggered discussions at age 10 that I didn’t see coming ;)
And when it comes to grasping stock market investing, an abstract and virtual topic these days, I can only encourage you to do the same.
Concretely, open the brokerage app with your child this weekend, show them the real amount they have invested, and let the questions come. It’ll be a giant leap for their financial education, you’ll see.
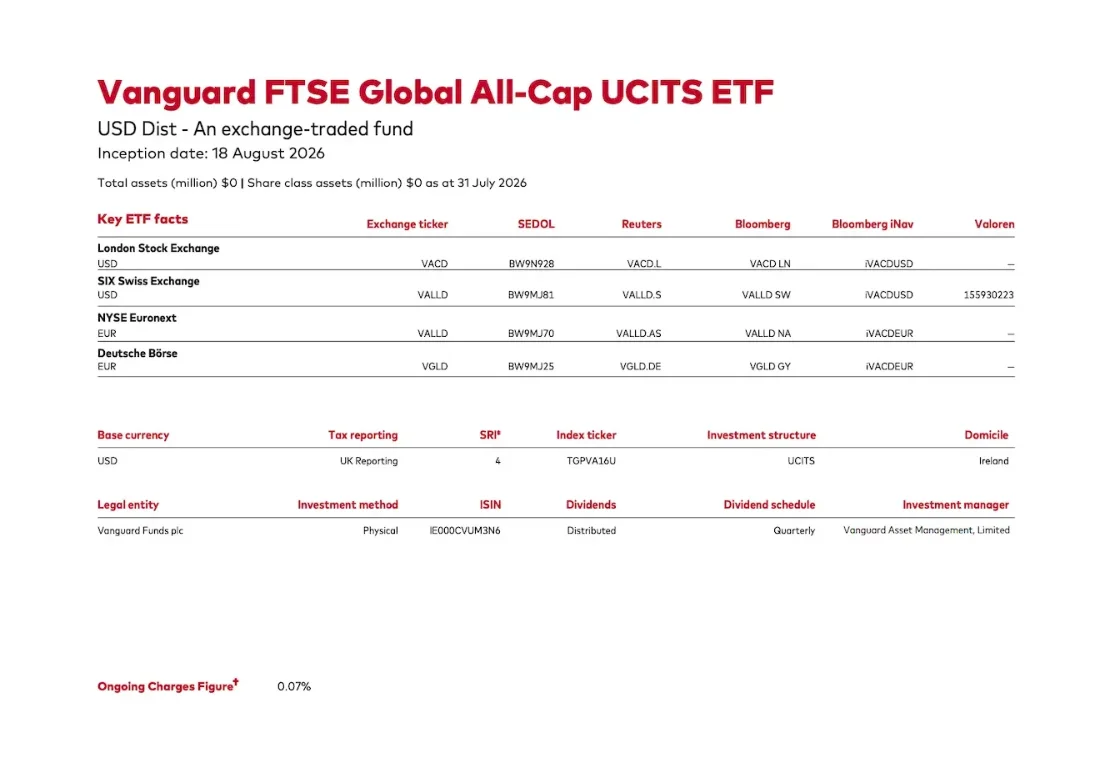
By the way, if you’re wondering which brokerage account and which ETF I use for our children, I broke it all down in a dedicated article: How to invest for your children in 2026?
In any case, it’s a real pleasure to be able to talk with your child about these topics I love so much. And above all, to see that they understand what I’m telling them. #ProudDad as they say, I guess ^^
And you, what question did your child ask when they saw their money? Tell me in the comments or by email, and I’ll add the best ones to a dedicated section of this article, along with your answer as a parent.
PS: as a personal finance geek, I confess it’s fun to now be able to say to one of my kids: “So, did you check your IBKR account? Or: did you see the dividends you received this morning? Followed by: we’ll need to reinvest them (so, hands off! haha)”
FAQ: parents’ questions about IBKR for kids
How do I set the “kid” IBKR account to read-only?
You first log into the IBKR app on your own phone (as the parent), with full access rights if asked. Then you let your child log in, and it will ask you whether you want to disconnect the other session or just connect in “read-only” mode. You choose “read-only”, and that’s it.
That way, at the beginning, we avoid my daughter placing buy orders by accident ;) But she can still follow her stock market investments.
Do I have to start from scratch, or can I reuse my Interactive Brokers account?
You have two options: either you use the sub-accounts option (starting from your existing Interactive Brokers account), or you create a new IBKR account for each of your children (each new account stays in your name, but you act “as if” it were theirs).
I explain how I set this up in this article: How to invest for your children in 2026?
The teen’s phone number or the parent’s for the login?
I used my own phone number. But that need is temporary, because afterwards you use Face ID or a similar 2FA method to log into your Interactive Brokers account.
As for the email address, to keep track of all my IBKR accounts (ours, our company’s, our kids’), I use the very handy Gmail feature that lets you have several addresses that all forward to your main account.
For example, if your email is firstname.lastname@gmail.com, you can do:
firstname.lastname@gmail.comfor your main IBKR accountfirstname.lastname+kid1-ibkr@gmail.comfor your first child’s IBKR accountfirstname.lastname+kid2-ibkr@gmail.comfor your second child’s IBKR accountfirstname.lastname+companyname-ibkr@gmail.comfor your company’s IBKR account- And so on
And all emails sent to these addresses land in the firstname.lastname@gmail.com account ;)
And if you want more details on how to do this with Interactive Brokers sub-accounts, here’s a dedicated article: How to create multiple Interactive Brokers sub-accounts in 2026
How do I handle the security questions when opening the account?
Technically, the new IBKR account you create is in your name, so you’re the one who needs to know the answers to these questions. No matter who you share access with afterwards, you’re the one legally responsible for this account.
How do I transfer the account to my child when the time comes?
Technically, you won’t transfer this account to your child on the day they come of age (or later). An internal IBKR transfer requires both accounts to be in the same name, same identity and same country, so from parent to child, it’s a no-go.
So here’s how to go about it on transfer day:
- Have your child, now an adult ;), open an IBKR account
- Sell all the assets in the IBKR account in your name (no capital gains tax in Switzerland, so no worries on that side)
- Convert everything to CHF
- Transfer that cash in CHF to your Swiss bank account
- Send that cash to your child’s Swiss bank account (because you can’t send cash to another IBKR account that isn’t in your name)
- And while you’re at it, draw up a gift document for that amount to stay on the right side of the tax authorities (how much you can gift tax-free per calendar year depends on your canton: in Zurich, gifts to your children are fully exempt, and in Vaud it’s CHF 300'000, so check the limit in your own canton)
- Your child then transfers those CHF to their own IBKR account
- And buys back all the assets you previously had in the account in your name
- And you close the account you had created for your child
It’s a bit tedious, but hey, you only do this once per child.
Also, since there’s no capital gains tax, and no stamp duty at IBKR, it costs you two commissions and a spread, a few dozen francs.
And your child’s money stays out of the market for a day or two, that’s it. There’s little chance the market jumps +30% in two days, and it’s a good opportunity to explain the concept of getting in and out of the market to your child ;)


Last updated: October 22, 2026